What an Emergency Fund Is and Why It Matters
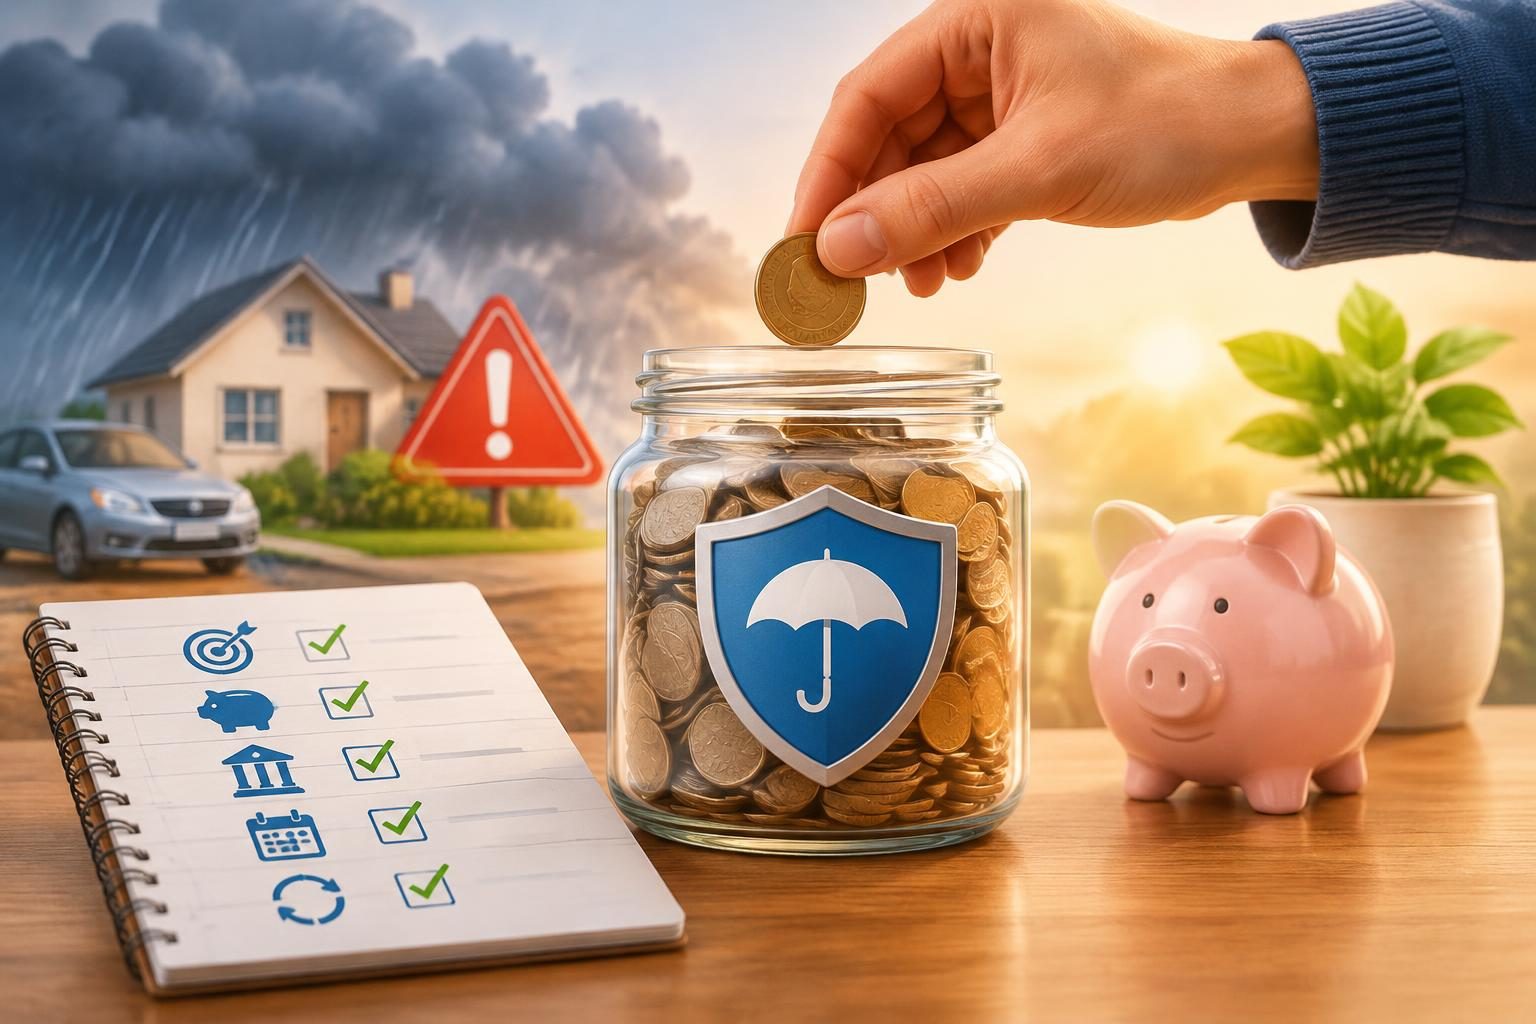
An emergency fund is money set aside for unexpected expenses that could otherwise disrupt your budget or push you into debt. It is designed for genuine emergencies, such as a sudden car repair, a medical bill, an essential home fix, or an unexpected loss of income.
The purpose of an emergency fund is simple: give you a financial cushion so you can handle surprises without relying on high-interest credit cards, loans, or short-term borrowing. Even a modest fund can make a stressful situation more manageable because it gives you time and flexibility to decide what to do next.
How Much to Save
A common starting goal is to save a small starter fund first, then build toward a larger reserve. If you are just beginning, aiming for one month of essential expenses can make the goal feel more realistic and easier to achieve.
A stronger long-term target is usually three to six months of essential living costs. That amount can help cover housing, utilities, food, insurance, transportation, and other necessary bills if your income is interrupted. The right target depends on your personal situation, including job stability, dependents, health needs, and how predictable your expenses are.
If saving a full emergency fund feels overwhelming, break it into stages. Focus first on the amount that would cover the most likely small emergencies, then increase the fund gradually until you reach a level that supports your finances with confidence.
Where to Keep Your Emergency Fund
An emergency fund should be easy to access when you need it, but not so easy that you spend it casually. A separate savings account is often the most practical place to keep it because it keeps the money apart from daily spending while still allowing quick access.
Many people prefer an account with limited friction, such as a basic savings account or high-yield savings account, because it helps the money stay available while remaining separate from checking. The main goal is safety and liquidity, not aggressive growth, since this money may need to be used on short notice.
Avoid tying emergency savings up in investments that can fluctuate in value or take time to sell. Money you may need soon should be kept in a place where it is protected from market swings and easy to withdraw when a real emergency happens.
How to Start Building It
Begin with a clear, specific target based on your monthly essentials. Once you know the number, divide it into smaller milestones so the goal feels manageable. For example, reaching your first small checkpoint can be more motivating than thinking only about the final total.
Look for money already in your budget that can be redirected to savings. Even small amounts add up over time when you save consistently. Consider trimming nonessential spending, setting aside windfalls, or pausing purchases that are not urgent while your emergency fund is still growing.
It can also help to define what counts as an emergency. When you know in advance what the fund is for, it becomes easier to avoid dipping into it for routine spending or planned expenses that should be covered by your regular budget.
How to Automate Contributions
Automation makes emergency saving easier because it removes the need to make a fresh decision every month. Setting up an automatic transfer from checking to savings can help you build the fund steadily and consistently.
A practical approach is to schedule transfers soon after each paycheck, before the money has a chance to be spent elsewhere. Even a small automatic transfer can create momentum and make saving feel less dependent on willpower.
If your income varies, you can still automate part of the process by choosing a conservative amount that fits your lowest-earning months. Then add extra contributions whenever you have additional income, such as from bonuses, side work, or a lighter spending month.
How to Use an Emergency Fund Wisely
An emergency fund works best when it is reserved for real, unavoidable needs. Before withdrawing money, ask whether the expense is unexpected, necessary, and urgent. That simple check can help protect the fund from being used too soon.
If you do need to use part of the fund, make a plan to rebuild it. Treat replenishing the account as a priority in your budget so the same emergency does not leave you exposed later. Rebuilding can happen gradually, as long as you keep moving toward your target.
The goal is not perfection. It is steady protection. A well-used emergency fund supports financial stability by helping you absorb shocks, avoid debt, and keep your larger financial plan on track.
A Simple Emergency Fund Plan You Can Follow
Step 1: Estimate your essential monthly expenses. Step 2: Choose a starter target that feels realistic. Step 3: Open or designate a separate savings account. Step 4: Set up automatic transfers. Step 5: Review your progress regularly and adjust your contributions as your income or expenses change.
If you already have some savings, decide how much should be kept available for true emergencies and how much can remain earmarked for other short-term goals. This helps your money have a purpose instead of sitting unplanned in one account.
Building an emergency fund is one of the most useful steps you can take toward financial security. With a clear target, the right account, and automatic contributions, you can create a buffer that supports you when life becomes unpredictable.