Understanding the Goal of a Debt Payoff Method
Choosing a debt payoff method is not just about paying as fast as possible. It is about finding an approach you can actually follow long enough to make steady progress. A good method should fit your cash flow, your total debt load, your interest rates, and your personality. If a plan feels too complicated or too discouraging, it is easy to abandon it before the balance starts to drop in a meaningful way.
The best debt payoff method is the one that helps you keep making payments, avoid new debt where possible, and stay motivated through the months it takes to see results. For some people, the most important factor is saving on interest. For others, the most important factor is seeing a balance disappear quickly so they feel encouraged to continue. Most people need a plan that balances both logic and motivation.
Before comparing methods, it helps to be clear about your real goal. Are you trying to pay off debt as cheaply as possible? Do you need quick psychological wins? Are you dealing with several high-interest balances at once? Are you worried about missing payments because your income changes from month to month? Your answers will point toward the method that fits your situation best.
Start With a Clear Picture of Your Debt
Before you choose a payoff strategy, list every debt you owe. Include the creditor, current balance, minimum payment, interest rate, and due date. If possible, also note whether the balance is fixed or revolving, and whether there are any fees, promotional rates, or penalties tied to late payment. A payoff strategy works better when you know exactly what you are dealing with.
This step matters because many people choose a method based on a vague sense of what they owe rather than the full picture. That can lead to a plan that looks good on paper but does not match reality. For example, a debt with a slightly higher balance may have a much lower interest rate than a smaller balance, and that difference can change the order in which you should attack the debt.
It also helps to separate debts into categories. Some debts are urgent because the interest rate is high. Some are urgent because the payment is large relative to your income. Some are urgent because missed payments create serious consequences. Once you can see your debt in one place, it becomes easier to compare payoff methods in a way that is practical instead of emotional.
The Main Debt Payoff Methods to Consider
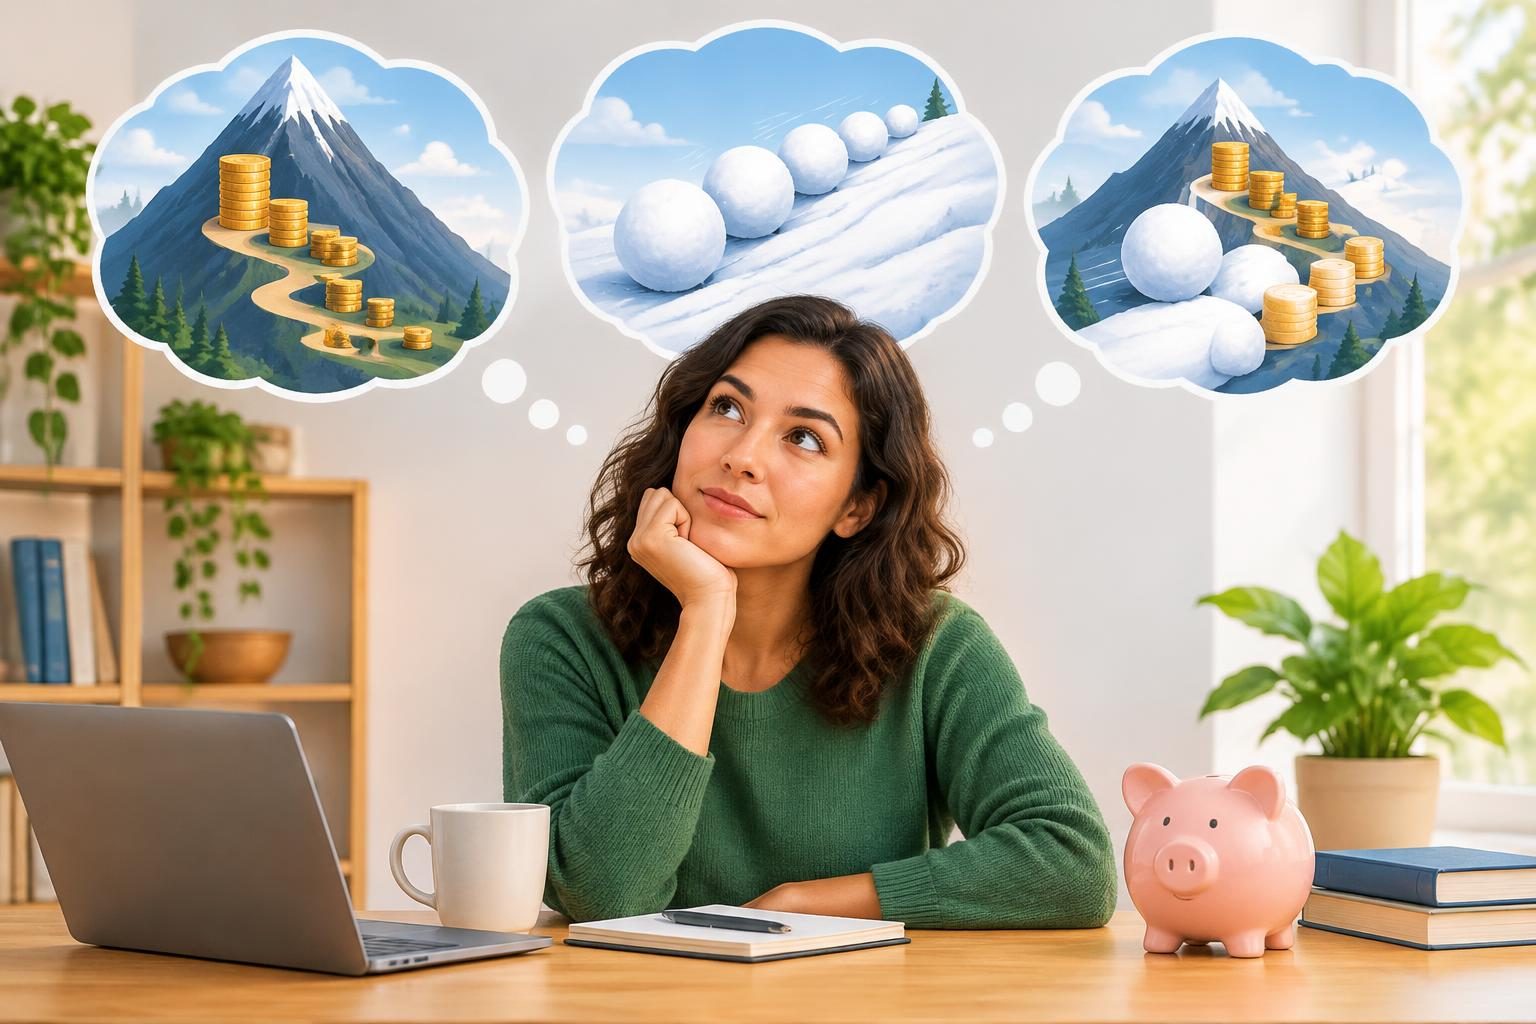
The two most common debt payoff methods are the debt avalanche and the debt snowball. Both can work well, but they emphasize different priorities. The avalanche focuses on the interest rate. The snowball focuses on the balance size. These are not the only possible approaches, but they are the best starting point for most people.
There are also hybrid approaches. Some people use an avalanche structure but choose a couple of quick wins first to build momentum. Others use a snowball structure for motivation, while still making sure that especially risky debts receive extra attention. In some cases, a person may choose to refinance, consolidate, or negotiate certain debts before using a payoff plan. The right method depends on the mix of debts and the person managing them.
Rather than asking which method is universally best, it is more useful to ask which method will keep you consistent. A strategy that you cannot maintain is less effective than a slightly less optimal strategy you will actually complete.
How the Debt Avalanche Works
The debt avalanche method tells you to make minimum payments on all debts, then direct any extra money toward the debt with the highest interest rate. Once that debt is paid off, you move to the debt with the next highest interest rate, and so on until all balances are gone.
The main advantage of the avalanche is mathematical efficiency. By attacking the highest-rate debt first, you reduce the amount of interest that accumulates over time. This can shorten the overall payoff timeline and lower the total cost of your debt repayment. If you have several balances with significantly different interest rates, the savings can be meaningful.
The avalanche is often a strong choice for people who are disciplined, comfortable with delayed gratification, and motivated by saving money. It can also be a good fit for people with larger balances or higher-rate revolving debt, because these are the debts most likely to grow expensive if left alone.
The challenge with the avalanche is psychological. The debt you pay first may not be the smallest balance, so it can take longer before you see a full account disappear. If visible progress matters a lot to you, that slower early momentum may make the method harder to stick with.
How the Debt Snowball Works
The debt snowball method tells you to make minimum payments on all debts, then put extra money toward the smallest balance first, regardless of interest rate. After that balance is eliminated, you roll the payment you were making into the next smallest balance. Each paid-off debt creates a larger payment for the next one, like a snowball gathering size as it moves forward.
The biggest advantage of the snowball method is motivation. Eliminating a small balance can feel rewarding very quickly, and that early win can help people stay engaged. If you have tried to pay off debt before and quit because progress felt too slow, the snowball may be a better match.
The tradeoff is that the snowball may cost more in interest than the avalanche if a higher-rate debt is ignored for a longer period. For some borrowers, that extra cost is worth it because motivation is what makes the plan sustainable. For others, especially those with large high-interest debts, a more interest-focused method may be the better long-term choice.
The snowball is often a good fit for people who need momentum, people who feel overwhelmed by debt, and people who benefit from finishing tasks one by one. It can also work well when the smallest balance is emotionally important, such as a loan that has been lingering for years.
Comparing Avalanche and Snowball in Real Life
If you are deciding between avalanche and snowball, think about what usually causes you to stop following a financial plan. Do you lose motivation when nothing seems to change? The snowball may help. Do you stay committed when you know a method is saving you money even if the progress looks slow? The avalanche may suit you better.
The difference between the two methods is often less about numbers and more about behavior. A mathematically efficient plan that you abandon is not truly efficient for your life. Likewise, a highly motivating plan that ignores very expensive debt may create unnecessary cost. The best choice is the one that gets you to the finish line.
A practical way to compare them is to list your debts in both orders. For the avalanche, rank them from highest interest rate to lowest. For the snowball, rank them from smallest balance to largest. Then ask yourself which sequence feels more doable. Sometimes the answer becomes obvious once you see the list in front of you.
Some people also find it helpful to calculate the difference in interest cost between the two methods. Even a rough comparison can show whether the savings from avalanche are modest or significant. If the difference is small, motivation may matter more. If the difference is large, the avalanche may deserve stronger consideration.
When the Avalanche Usually Makes the Most Sense
The avalanche often makes the most sense when interest rates vary widely, especially when one or more debts have very high rates. Credit cards are a common example. When the cost of carrying a balance is high, reducing that balance sooner can help you stop paying so much interest month after month.
It may also be the better choice if you are comfortable delaying gratification and prefer a plan built around logic. Some people feel more confident when they know every extra dollar is going toward the most expensive debt. That confidence can make the method feel disciplined and controlled rather than stressful.
The avalanche can be especially useful if you are making serious progress and want your money to work as efficiently as possible. If you already have a stable budget, a reliable income, and a strong ability to follow a plan without needing constant emotional reinforcement, the avalanche can be a very practical strategy.
This method also fits people who are focused on long-term financial optimization. If you are trying to free up cash flow while keeping overall debt costs as low as possible, and you can remain consistent without needing quick wins, the avalanche is often a strong default choice.
When the Snowball Usually Makes the Most Sense
The snowball often makes the most sense when your debt feels scattered and overwhelming. If several balances are hanging over you at once, clearing one account can create a strong sense of progress. That feeling can be especially valuable if debt has been causing stress or avoidance.
It is also a strong option when you need early proof that your plan is working. Some people are not motivated by abstract interest savings. They need a visible result. A paid-off account can make the process feel real and can reduce the temptation to give up before real progress begins.
The snowball may be especially helpful if your smallest balance is close to being paid off already. In that case, the time required to eliminate it may be short enough to create a fast win. Once that account is gone, the payment you free up can become a useful part of the next step.
If you have tried other payoff plans and failed because they felt too slow or too hard to maintain, the snowball can provide a simpler, more encouraging structure. For many people, confidence is not a minor detail. It is the thing that makes the entire plan possible.
Other Factors That Should Influence Your Decision
Interest rate is important, but it should not be the only factor. The size of your emergency fund matters too. If you have no buffer at all, an unexpected expense could force you back into debt even while you are making progress. A payoff plan that leaves no room for real life may break down when something goes wrong.
Your income stability also matters. If your income changes from month to month, you may need a more flexible plan than someone with a fixed salary. In that case, it can help to build a buffer for essential expenses before sending every extra dollar to debt. A payoff method should fit the way money actually comes in, not just the way you wish it would.
Minimum payments deserve attention as well. A debt with a large minimum payment can strain your budget even if the balance is not the highest. If a required payment is too large, it may be more urgent to stabilize cash flow than to rank the debt based only on balance or interest rate.
Emotional stress matters too. Some debts carry a heavier mental burden than others. You may feel differently about a personal loan, a credit card, or a medical bill. A method that ignores your emotional reality can be harder to follow. The goal is not only to eliminate debt mathematically, but also to create a plan you can live with day after day.
How to Choose the Right Method for Your Situation
A simple decision process can help. First, ask whether saving the most interest is your top priority. If yes, the avalanche is usually the first method to consider. Next, ask whether motivation is your biggest challenge. If yes, the snowball may be the better starting point. If both matter, consider a hybrid approach.
You can also compare your debts by urgency. Debts with very high rates are usually strong avalanche candidates. Small balances that are close to being paid off are often strong snowball candidates. If one debt creates a lot of stress but is not the most expensive, you may decide to address it early anyway because peace of mind helps you stay on track.
Another useful question is this: which method will you still follow three months from now? It is easy to choose a strategy based on what sounds smart in theory. It is harder to choose one that fits your habits, your personality, and your current money situation. If you tend to lose interest in slow plans, choose the method that gives you quicker reinforcement.
If you are unsure, start with the method that seems most realistic and commit to reviewing it after a set period. A debt payoff method is not a lifetime identity. It is a tool. If your situation changes, your strategy can change too.
How to Build a Simple Debt Payoff Plan
Once you choose a method, turn it into a concrete plan. Write down every debt, the minimum payment, and the order in which you will pay extra. Decide how much extra money you can realistically apply each month after essentials are covered. The plan should be specific enough that you do not have to rethink it every time you sit down to pay bills.
A helpful next step is to connect your payoff plan to your budget. Identify spending categories where you can free up money for debt repayment. This may involve reducing dining out, subscriptions, impulse purchases, or other nonessential spending. The goal is not to live uncomfortably, but to direct money toward the balances that are costing you the most.
Then decide how you will track progress. You can use a spreadsheet, a budgeting app, a notebook, or a simple checklist. What matters is that you can see the remaining balances and celebrate each completed step. Tracking helps you stay focused and makes progress feel more tangible.
It can also be useful to set a monthly review date. At that time, check whether the plan still fits your income and expenses. If you receive a raise, cut a recurring bill, or pay off one debt, update the plan so the freed-up money goes to the next target instead of drifting away unnoticed.
A Step-by-Step Example of Choosing Between Methods
Imagine you have three debts: one credit card with a high interest rate and a medium balance, one small personal loan with a lower rate, and one larger store card with a moderate rate. If you use the avalanche, you would compare interest rates first and direct extra money toward the highest-rate account. That may reduce total interest the most.
If you use the snowball, you would likely pay off the smallest balance first, even if its rate is lower. That could give you a quick success and help you stay motivated. Once that account is gone, you would roll its payment into the next smallest debt.
Now ask which matters more in your life right now: lower interest cost or easier follow-through. If you are already disciplined and want the most efficient math, the avalanche may be best. If you feel discouraged by debt and need early proof that the plan works, the snowball may be better.
The point of the example is not to prove one method is always superior. It is to show how the same set of debts can lead to different choices depending on your personality and priorities. That is why choosing a payoff method is both a financial decision and a behavior decision.
Common Mistakes to Avoid When Choosing a Payoff Method
One common mistake is choosing a method because it sounds impressive rather than because it fits your life. A strategy does not need to be fancy to work. It needs to be sustainable. Simplicity is often more valuable than complexity.
Another mistake is ignoring interest rates entirely. While motivation matters, some debts are simply too expensive to leave untouched for long periods. Even if you prefer the snowball, you should still be aware of how much high-interest debt is costing you. Otherwise, you may underestimate the importance of faster repayment on certain balances.
A third mistake is failing to include minimum payments in the budget. A payoff plan that only focuses on extra payments can collapse if the base payments are already too high. Make sure the required payments fit within your monthly cash flow before committing to a method.
People also sometimes switch methods too often. Changing plans every few weeks can make it hard to build momentum. It is reasonable to adjust when your situation changes, but avoid constantly restarting the decision process. Once you choose a method, give it time to work unless there is a clear reason to revise it.
When a Hybrid Approach Can Be Better
A hybrid approach can be useful when neither pure avalanche nor pure snowball feels right. For example, you might start with a small balance that is close to disappearing, then switch to the highest-interest debt. That can give you an early win without ignoring long-term cost.
Another hybrid option is to set a rule that any debt above a certain interest rate gets priority, while smaller balances below that threshold are handled in order of size. This can help you keep the structure of the avalanche while still respecting the motivational power of the snowball.
Some people also use a hybrid because their debt list contains both urgent and nonurgent accounts. A debt with a high rate may deserve the first extra payment, while a tiny balance may be worth clearing quickly to simplify the number of accounts they have to manage. The goal is to create a payoff order that feels logical and encouraging at the same time.
If you choose a hybrid, keep the rules simple. The more exceptions you create, the harder the plan becomes to follow. A good hybrid method still needs a clear order, a clear extra payment target, and a clear way to move to the next debt once a balance is eliminated.
How to Stay Motivated During the Payoff Process
Debt payoff usually takes time, so motivation matters. One of the best ways to stay engaged is to make progress visible. Mark paid-off debts on a chart, update balances regularly, or keep a running total of how much principal you have eliminated. Small signs of progress can keep the process from feeling endless.
Another way to stay motivated is to attach your payoff plan to a meaningful goal. Maybe you want less stress, more flexibility in your budget, or room to save for the future. When the process feels repetitive, remembering the reason behind it can help you keep going.
It also helps to celebrate progress in low-cost ways. You do not need to reward every milestone with a big purchase. Simple recognition can be enough. For example, you might acknowledge each debt payoff with a note, a walk, or an activity you already enjoy. The point is to reinforce the habit without creating new debt.
If you struggle with motivation, consider accountability. You may share your goals with a trusted person, review your plan with a partner, or set a recurring check-in date for yourself. The more visible the plan is, the more likely you are to keep following it.
How to Adapt Your Plan If Your Situation Changes
A good debt payoff method should be flexible enough to handle real life. Income changes, unexpected expenses, and shifts in interest rates can all affect your plan. If you receive a raise or reduce a recurring cost, you may be able to send more money to debt. If your income drops temporarily, you may need to focus on minimum payments and protect essentials first.
If an emergency expense appears, do not assume your plan has failed. A temporary adjustment is often better than forcing payments that create more debt elsewhere. In some cases, pausing extra payments briefly to handle a true emergency is the responsible choice, especially if it keeps you from falling behind on essential bills.
When a major change happens, review the entire debt list again. A balance that was once the right target may no longer be the best one to attack first. The point of the plan is to support your financial health, not to trap you in a rule that no longer fits your situation.
Flexibility is especially important if you are dealing with variable income. In those cases, your debt payoff method may need to work alongside a stronger emergency cushion and a careful budget. That does not make the plan weaker. It makes it more realistic.
Putting It All Together
The right debt payoff method is the one that matches your numbers and your behavior. If you want to minimize interest and can stay consistent without needing quick wins, the avalanche may be a strong fit. If you need visible progress to stay motivated, the snowball may be the better choice. If your situation is mixed, a simple hybrid can give you both structure and encouragement.
To choose well, start with a full list of your debts, compare balances and interest rates, and think honestly about what keeps you moving. Do not choose a method based only on what sounds best in theory. Choose the method you are most likely to follow through on, even when the process feels slow.
Once you decide, turn the method into a clear monthly plan. Make minimum payments on everything, put extra money toward the chosen target, and review your progress regularly. As debts disappear, roll those payments forward so your momentum grows instead of fading. Over time, consistency matters more than perfection.
Debt payoff is rarely exciting every day, but a well-chosen method can make it manageable. By matching your strategy to your situation, you give yourself a better chance of staying on track long enough to finish what you started.